Designing Mobile Content Playlists for Different Client Personas
Key Takeaways
- A large approved mobile content library does not help advisors if they cannot quickly identify the material that fits a client’s situation and the conversation at hand.
- Persona based playlists give advisors a practical path to relevant, approved content while keeping distribution inside the firm’s supervision and recordkeeping framework.
- Effective playlists are built around client needs, decision points, and relationship stages, not age or asset level alone.
- Governance belongs in the design of the playlist, including approvals, permissions, current version controls, retention, and clear ownership.
- The strongest measure of playlist value is not content volume or raw views. It is whether advisors use the material to support more relevant, consistent client conversations.
Article at a Glance
A retiree concerned about dependable income, a business owner considering a sale, and an accumulator building long term wealth should not receive the same sequence of content. Yet many firms still give advisors a broad library, a search bar, and little guidance on what belongs in a specific client conversation.
That creates a familiar operational problem. Advisors either rely on a small set of familiar materials, spend too much time searching, or create informal workarounds outside approved systems. The client receives content that feels generic. Compliance teams lose visibility. Marketing cannot tell which material supports productive conversations.
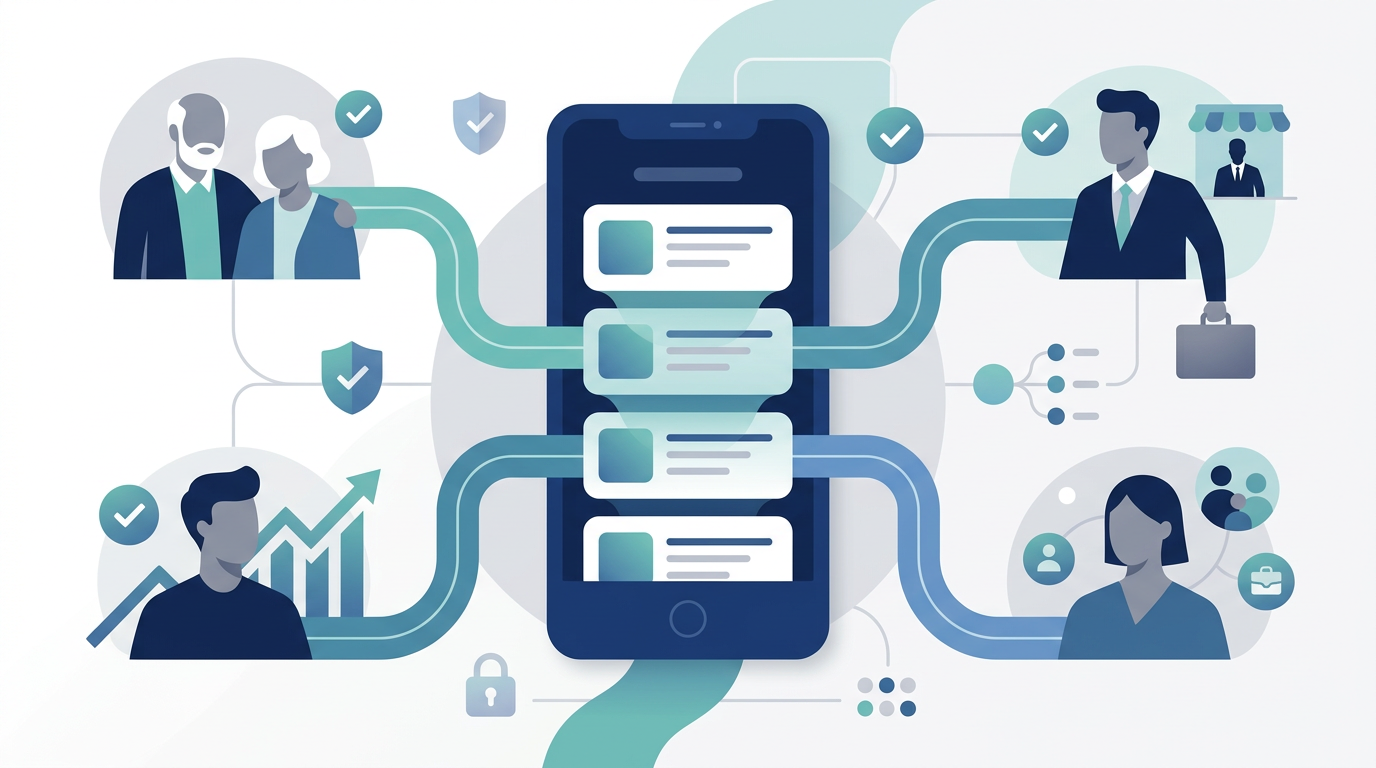
A mobile content playlist solves a narrower but important problem. It gives an advisor a curated sequence of approved resources for a defined client situation, available when the advisor is preparing for a meeting or responding to a follow up question. The playlist is not a substitute for professional judgment. It is a controlled way to make relevant content easier to use.
For firms with regulated communications obligations, the design matters as much as the content itself. A playlist must support relevance without allowing outdated, unapproved, or unsuitable materials to circulate through informal channels.
The Cost of Generic Content Sharing
Most firms do not have a content shortage. They have a content retrieval and distribution problem.
Over time, marketing teams create market commentary, planning guides, videos, email campaigns, explainer pieces, and presentation materials. Compliance reviews them. The library grows. Then an advisor preparing for a meeting with a pre retiree has to decide which of several hundred approved pieces will help that client understand a complex planning decision.
Without an organizing model, the easiest choice is often the least useful one. The advisor sends the same market update to every client. Or they avoid sharing anything because finding the right resource takes too long. A more concerning outcome is the use of personal email, unapproved messaging tools, downloaded files, or links copied from a public browser.
The problem is not that advisors lack care. It is that the system expects them to perform curation, compliance judgment, and client relevance assessment in the few minutes before a meeting.
That burden becomes more visible on mobile. Field teams and advisors need content that is available in the moment, readable on a small screen, and easy to share through a supervised workflow. A desktop portal with an extensive library can satisfy a storage requirement while still failing the advisor who needs a relevant, current resource during a client interaction.
Relevance Is Part of the Client Experience
Clients interpret content through the context of their own lives. A client approaching retirement is likely to have different questions from a business owner preparing for a liquidity event. An inheritor facing unfamiliar financial responsibilities may need a slower, more educational sequence than a client who has spent years actively managing investments.
When content regularly misses the moment, the issue is larger than low engagement. It suggests that the firm does not understand the client’s priorities. That impression can weaken confidence in the advisory relationship, even when the underlying advice is sound.
Content Marketing Institute’s 2025 guidance on audience segmentation similarly emphasizes using audience information to deliver content aligned with what readers need and when they need it. The principle applies directly to advisor communications, with the added requirement that firms manage relevance within their own supervisory standards.contentmarketinginstitute
Mobile Does Not Remove Supervisory Duties
The device does not determine whether a communication needs oversight. The content and business purpose do.
FINRA states that its communications rules apply to social media and that business related communications must be retained based on their content rather than the device or technology used to send them. FINRA also requires firms to be able to supervise business related content communicated by associated persons.finra
For broker dealers, FINRA Rule 2210 addresses approval, content standards, and retention requirements for communications with the public. The rule requires retention of retail and institutional communications and records related to approval and use.finra
For registered investment advisers, the SEC’s marketing rule and related books and records requirements impose obligations tied to advertisements and certain marketing activities. Applicability depends on the firm, the communication, and the facts involved, so firms should have qualified compliance and legal professionals evaluate their own use cases.sec
A mobile playlist should therefore be treated as part of the firm’s communication infrastructure. It should help advisors stay inside approved channels, not create another path around them.
What a Governed Playlist Looks Like
A mobile content playlist is not a folder of PDFs. It is a curated sequence of preapproved materials organized around a defined client persona, client question, or planning moment.
A strong playlist provides three things at once.
- It gives the advisor a practical path through approved content.
- It gives the client a more coherent educational experience.
- It gives compliance and operations teams a controlled method for maintaining visibility over what is available and what is shared.
The sequence should mirror how a client conversation develops. A pre retiree playlist, for example, may begin with an educational resource about retirement readiness, continue with a general discussion of risk and income planning, and include a follow up resource that helps the client prepare for the next meeting. It should not attempt to provide individualized advice through content alone.
The goal is not to automate every interaction. It is to reduce avoidable friction. Advisors still need to decide which approved material is appropriate, when to use it, and when a client’s question requires a more direct conversation.
Personalization Has Boundaries
Personalization in a regulated setting does not mean allowing every advisor to create custom materials on the fly. It means helping advisors choose the most relevant items from a controlled set of approved options.
That distinction matters. A centrally governed library can provide flexibility in selection while retaining standards for review, disclosure, version management, and retention. Advisors gain a clearer path to useful content. Compliance teams avoid the impossible task of reconstructing ad hoc distribution after the fact.
The most effective systems create those boundaries before a client interaction occurs.
Build Personas Around Decisions, Not Labels
A persona should describe a recurring client context that changes what the advisor needs to explain, what the client is likely to ask, and what content will be useful. It should not be a superficial label based only on age, income, or account size.
Demographics can be useful inputs. They are not enough to determine a playlist.
A 58 year old executive, a 58 year old business owner, and a 58 year old newly divorced client may share an age range while facing very different financial decisions. Their relevant content pathways will differ accordingly.
A practical persona model considers the following dimensions.
| Persona dimension | What it helps determine |
| Financial priorities | The planning topics and client questions that should shape the playlist |
| Decision horizon | Whether the content should support immediate action, ongoing education, or long range planning |
| Relationship stage | Whether the advisor needs introductory material, decision support, or follow up resources |
| Complexity | Whether content should prepare the client for coordination with tax, legal, insurance, or other qualified professionals |
| Communication preference | Which formats are most useful, such as short articles, videos, meeting materials, or follow up guides |
A firm does not need dozens of personas. In many cases, three to five clearly defined groups provide a manageable starting point. The test is operational usefulness. If a persona does not lead to a meaningfully different content path, it may not need its own playlist.
Common Persona Patterns
The following examples are illustrative. Each firm should define its own personas based on its client base, service model, approved offerings, and supervisory requirements.
The Accumulator
This client is building wealth, making career decisions, and trying to understand market conditions in the context of long term goals. A useful playlist may focus on foundational planning concepts, long term investment education, tax aware considerations, and periodic market context.
The content should help the advisor move from broad interest to an informed planning conversation. It should not presume that every client in this group has the same risk tolerance, goals, or investment needs.
The Pre Retiree
This client is approaching a major transition and is likely weighing income needs, portfolio risk, health care considerations, timing decisions, and lifestyle expectations. Content needs to be clear, practical, and sensitive to the stakes without becoming alarmist.
A playlist may include retirement readiness education, explanations of income planning concepts, market context, and discussion prompts for the next planning meeting. Topics such as Social Security, tax implications, and health care planning should be addressed only within the firm’s approved content and appropriate professional boundaries.
The Retiree
A retiree often wants clarity about income, volatility, withdrawal planning, and whether the existing plan remains aligned with changing circumstances. The advisor’s relationship and communication cadence are especially important here.
A playlist for this persona should prioritize plain language, timely context, and materials that support ongoing review. Dense documents and generic growth messaging are unlikely to help an advisor create a useful conversation.
The Business Owner
Business owners usually face overlapping personal and business considerations. Cash flow, compensation, valuation, succession, liquidity, tax planning, and family goals may all intersect.
The most useful content is organized around the decision the owner is actually facing. A client considering a future sale needs a different sequence from one focused on growth or succession. The playlist should also reinforce the need for coordinated work with qualified legal, tax, and other professionals where appropriate.
The Inheritor or Newly Wealthy Client
This client may have significant assets but limited confidence in managing unfamiliar choices. The early content sequence should support understanding and trust before it moves toward more complex planning discussions.
An effective playlist for this persona tends to emphasize education, orientation, and questions to consider. The tone should be respectful and clear. It should not assume that a client with substantial assets already understands the decisions in front of them.
A Five Part Playlist Design Model
A useful playlist program requires more than content tagging. It requires a repeatable operating model that connects client needs, advisor workflow, and governance.
1. Define the Client Context
Begin with the real client questions advisors hear most frequently. Review meeting notes, client service patterns, advisor input, planning workflows, and approved marketing priorities.
The objective is to identify the questions that recur within a persona at specific relationship stages. A business owner preparing for a potential sale may ask about valuation, timing, taxes, and life after liquidity. A retiree may ask how market volatility affects income needs. Those questions should guide playlist design.
Avoid starting with the existing content library. Starting with available assets can cause firms to build playlists around what they have rather than what clients need.
2. Audit and Tag Approved Content
Once the firm defines the client contexts, it can review the existing library. Each approved asset should have a consistent set of tags.
| Content tag | Purpose |
| Persona fit | Identifies the client situations for which the material is likely to be relevant |
| Topic | Organizes material around planning, market context, business ownership, retirement, or other approved categories |
| Conversation stage | Distinguishes discovery, education, decision support, and follow up content |
| Format | Helps advisors select a short article, video, presentation, or guide that suits the setting |
| Approval status | Confirms whether the item is currently available for use |
| Review date | Supports timely review, refresh, or removal of older content |
This taxonomy gives marketing, compliance, and advisors a shared language. It also prevents a playlist from becoming an unmanaged collection of materials that happened to be relevant at one point in time.
3. Sequence Content Around the Conversation
A playlist should reflect the order in which a client is likely to need information.
For example, a retiree sequence might begin with a general planning resource before moving to approved market context and then a guide that supports a follow up discussion. A business owner sequence may begin with an educational overview of business transition planning before moving toward materials that help the client identify questions for their accountant, attorney, and advisor.
The advisor should be involved in this work. Marketing can organize assets, but advisors understand the conversations where clients hesitate, ask for clarification, or need time before making a decision.
A practical design exercise is to identify three to five recurring client questions for each persona and map approved resources to those questions in the order they usually arise.
4. Apply Access and Approval Controls
A playlist should only contain content that is approved for the intended audience and use case. Firms also need a clear rule for who can access, edit, share, approve, and retire materials.
Role based access can help reduce clutter and simplify advisor choices. It can also support a firm’s internal permissions model by giving teams access to playlists relevant to their practice focus and authorization level.
The governance approach should cover:
- Approval before content enters the available library
- Version control and removal of superseded materials
- Documented ownership for playlist review and updates
- Permissions that reflect advisor roles and practice focus
- Supervised distribution channels
- Retention and retrieval capabilities appropriate to the firm’s obligations
FINRA Rule 2210 requires firms to retain specified communications and approval records, while FINRA’s guidance emphasizes written supervisory procedures for business related electronic communications. Firms should confirm how their own policies apply to mobile content delivery, client sharing, and related records.finra+1
5. Build the Playlist Into Advisor Workflow
A playlist is only useful if advisors can find it when they need it. That means the system should be simple enough to use before a meeting, during preparation, or in an appropriate client follow up workflow.
The advisor should not need to search through hundreds of items, interpret approval codes, or switch between multiple systems to determine whether an asset is current.
The best workflow is often the least dramatic. The advisor selects a client context, sees a small number of relevant approved resources, chooses the appropriate item, and shares it through the firm’s controlled process. The system captures the necessary record without adding unnecessary steps.
The Governance Layer That Makes Scale Possible
Firms sometimes treat governance as a late stage compliance review. That approach creates rework because the playlist structure itself affects how content is selected, distributed, retained, and supervised.
Governance needs to be part of the original design.
Preapproval Should Happen Upstream
Preapproval gives advisors confidence that available material has passed through the firm’s review process. It also narrows the field decision to a more manageable question: which approved item best fits this client conversation?
That does not eliminate supervision. It changes where the work happens. Rather than expecting an advisor to assess every item under time pressure, the firm builds controls into the content lifecycle.
For FINRA member firms, Rule 2210 includes requirements related to principal approval of certain retail communications before use, subject to applicable exceptions and facts. Each firm should determine how its own supervisory procedures apply to content playlists, interactive communications, and mobile distribution.finra
Version Control Is Not Administrative Detail
Financial content can become stale quickly. Market commentary changes. Planning materials may require updates. Product related content can be superseded. Rules, disclosures, and firm policies can change.
A governed system needs a way to identify the version that was available at the time of sharing and remove materials that are no longer current. That record can matter during an internal review, client inquiry, or regulatory examination.
A quarterly refresh cycle is useful for many firms, but the appropriate cadence depends on the type of content and the firm’s policies. Time sensitive market materials may need review much sooner. Foundational educational content may have a longer review cycle.
Measurement Must Respect the Communication Framework
Usage data can improve playlist design, but firms should measure what they can use responsibly within their approved technology and recordkeeping environment.
Useful indicators include:
- Advisor use by persona and playlist
- Frequency of use before or after client meetings
- The assets most commonly selected by advisors
- Client engagement where the firm’s approved systems can capture it
- Advisor feedback on missing content or confusing sequences
- The age and review status of materials in each playlist
Raw views are not enough. A heavily viewed asset may be useful, but it may also be the first item advisors see because it is poorly categorized. Firms should look for patterns that show whether playlists support better preparation and more relevant client discussions.
Three Illustrative Use Cases
A Regional RIA Seeking Consistency
A regional RIA has several advisors serving accumulators, retirees, and business owners. Each advisor has access to the same approved content library, but client communications vary widely. Some advisors use content regularly. Others avoid it because the library feels too broad.
The firm creates three initial playlists based on the client groups that make up most of its book of business. Marketing tags and sequences approved content. Compliance establishes review and update rules. Advisor leaders test the playlists in client preparation.
The expected benefit is not uniformity for its own sake. It is a more consistent baseline for relevant content use. Advisors retain judgment, while the firm creates a clearer path for approved client education.
A Solo Advisor With Two Distinct Client Groups
A solo advisor works primarily with retirees and younger professionals. Before meetings, the advisor spends time locating old email attachments, saved web pages, and downloaded materials.
The advisor’s firm creates two compact playlists from existing approved assets. One centers on retirement and ongoing income planning education. The other supports long term planning and market education for accumulators.
The value is practical. The advisor can prepare more quickly, use firm approved materials, and create a more coherent follow up process without building a personal content archive outside firm systems.
A Broker Dealer Managing Scale
A broker dealer with a large representative network faces a more complex issue. Advisors use different communication methods, content resources, and client segmentation approaches. The firm cannot solve that problem by simply adding more assets to its portal.
A structured playlist program can create common governance standards while allowing different practice groups to use content that fits their clients. The firm needs clear rules for permissions, supervisory review, training, retention, and content updates before broad distribution begins.
At this scale, the operating model matters as much as the mobile platform. A poorly governed rollout can create more complexity. A well designed program can reduce it.
Frequently Asked Questions
How many personas should a firm create?
Start with the smallest number that reflects meaningful differences in client needs and advisor conversations. Three to five personas are often easier to govern and maintain than a large collection of narrow segments. Add more only when the additional persona changes the content path in a material way.
Can preapproved content still feel personal?
Yes. Personalization does not require custom content for every client. An advisor can select the most relevant approved material, use it at the right point in the relationship, and connect it to the client’s stated questions. The approved asset stays controlled while the advisor applies judgment to the context.
Who should own the playlist program?
No single function can own the entire program alone. Marketing typically manages content strategy and curation. Compliance manages review requirements and supervision standards. Technology manages delivery capabilities and integrations. Advisory leadership defines the client contexts and reinforces adoption. A named cross functional owner should coordinate the work.
How should firms handle changing market conditions?
Firms should establish a review process for time sensitive materials and identify who can replace, pause, or remove content when conditions change. Advisors need a clear source for current approved market context rather than an incentive to find and distribute outside materials.
Do all mobile shares require the same review process?
The answer depends on the firm’s regulatory status, the type of content, the intended audience, the communication channel, and the firm’s written supervisory procedures. FINRA guidance distinguishes among forms of communication and addresses supervision of interactive electronic communications. Firms should rely on their compliance and legal teams to apply the requirements to their specific workflows.finra+1
What technology capabilities matter most?
The most important capabilities are not flashy. Firms need current approved content, permissions, searchable metadata, mobile usability, version management, audit trails, retention support, and integration with existing compliance and advisor workflows. A platform should reduce advisor effort rather than simply move an unstructured library onto a phone.
Make Relevant Content Easier to Use
A firm can begin without redesigning its entire marketing operation. Identify the client groups that matter most, map the questions those clients bring to advisors, and audit the approved content already available. That work usually reveals both useful assets and significant gaps.
The next decision is whether the firm has a governed way to deliver that content where advisors actually work. FMEX helps financial organizations assess their mobile content workflow, from approved library design and persona based playlist structure to advisor access, governance, and usage visibility. Contact FMEX to discuss a compliance first mobile content assessment tailored to your technology stack, advisor workflow, client journey, and business goals.